Tax guide · 5 min read
Placed in service by year-end: evidence for 2026 equipment purchases
Buying equipment in 2026 is not enough to start depreciation. Learn what placed in service means and what Houston businesses should document before year-end.
A signed order or paid invoice does not, by itself, establish that business equipment was placed in service in 2026. For federal depreciation, the key date is generally when the property is ready and available for its specific business use.
That distinction matters when a Houston business buys machinery, computers, furniture, vehicles or other equipment near year-end. Delivery, installation, testing, customization and actual availability may occur on different dates.
This guide explains the placed-in-service rule and the records a small business should keep. It does not determine whether a particular purchase qualifies for Section 179, bonus depreciation or another deduction.
Placed in service means ready and available
IRS Publication 946 states that property is placed in service when it is ready and available for a specific use. Depreciation begins when the property is placed in service for use in a trade or business or for producing income.
Actual daily use is not always required. Equipment can be placed in service when it is fully ready and available even if the first customer job happens later. But equipment that still needs essential installation, modification or testing generally has not reached that point.
The IRS gives a machine example: delivery occurred in one year, but the machine was not installed and operational until the next year. It was placed in service only when installation made it operational. Publication 946 also describes a modified truck as placed in service when the lifting equipment was completed and the truck was ready for its intended function.
Ordering, paying and delivery are different events
A year-end purchase file may contain several dates:
- purchase order date;
- contract or financing date;
- invoice date;
- payment date;
- shipping date;
- delivery date;
- installation date;
- testing or acceptance date; and
- date the equipment became ready for business use.
None of the first six dates automatically controls every situation. A boxed computer delivered December 30 may be ready quickly, while specialized machinery delivered the same day may need weeks of electrical work, calibration and safety testing.
Do not change an installation or acceptance record merely to obtain a 2026 deduction. Use the operational facts and keep contemporaneous evidence.
Build a placed-in-service evidence file
For equipment that becomes ready before December 31, retain records that show what happened and when. Depending on the asset, useful evidence may include:
- vendor invoice and purchase agreement;
- proof of delivery and serial number;
- installation work order;
- contractor completion record;
- electrical, network or utility connection record;
- configuration or calibration report;
- inspection or permit approval, when required;
- test-run log or production output;
- employee training or handoff record;
- insurance schedule;
- fixed-asset register entry;
- dated photographs of the installed asset; and
- a short management note identifying the intended business use and the date the asset became ready.
One document rarely proves the entire timeline. The strongest file connects delivery, installation, testing and availability with consistent dates.
Use a simple readiness test
Before treating a 2026 purchase as placed in service, ask:
- What specific business function was the asset acquired to perform?
- Was the asset physically delivered to the location where it would operate?
- Were essential installation and modifications complete?
- Could the asset perform its intended function by year-end?
- Were required inspections, permits or system connections complete?
- Was it available to the business, even if no customer job occurred yet?
- Do independent records support that date?
If the answer to a necessary step is no, the asset may belong in a later placed-in-service year. A preparer should review the full facts rather than relying on an internal spreadsheet date alone.
Examples of year-end timing
Delivered and operational
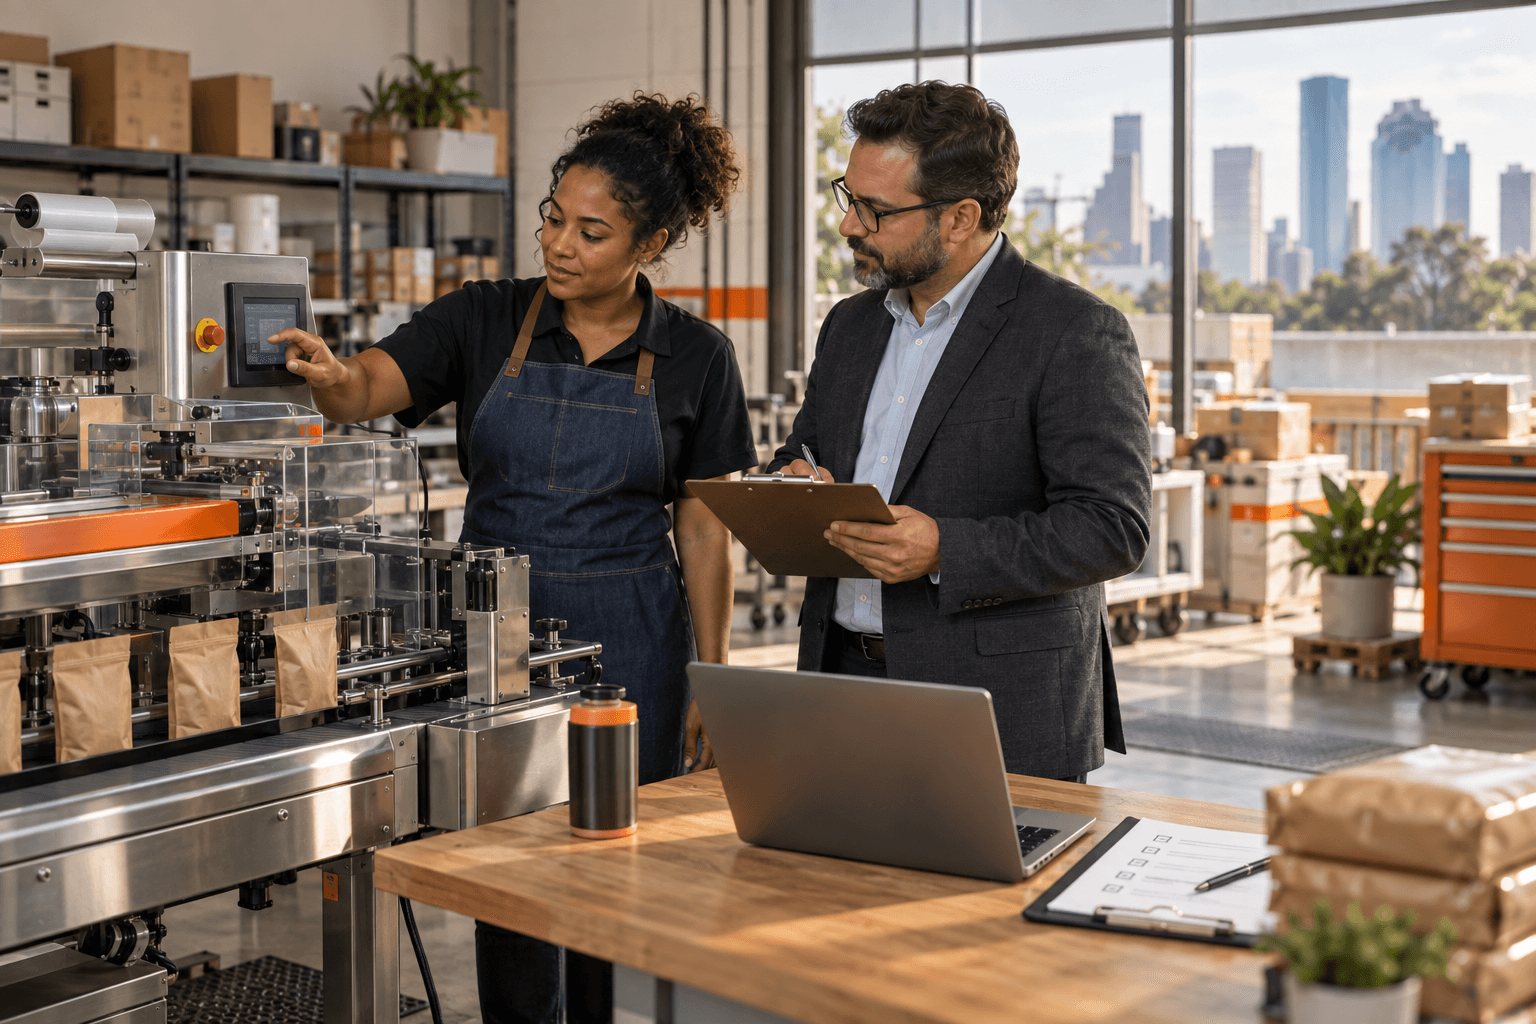
A packaging machine arrives December 18. Installation and testing finish December 27, and the machine is ready to package products. The business does not run its first full order until January. The operational records may support a December placed-in-service date because the machine was ready and available for its specific use.
Delivered but waiting for installation
The same machine arrives December 18 but requires a new electrical circuit and vendor calibration. That work finishes January 8. A December invoice and delivery receipt do not make the machine operational in December.
Furniture in an unfinished location
Office furniture is delivered to a new location, but construction prevents employees from using the space until January. The business should review when the furniture and location were actually ready for their intended use instead of assuming delivery settled the question.
Equipment converted from personal use
When property moves from personal use to business or income-producing use, Publication 946 treats the business placed-in-service date as the date of conversion. Keep a record of that change and the business-use basis determination.
These examples illustrate the analysis. Small differences in installation, access, permits and intended function can change the conclusion.
Placed in service is only one depreciation question
A supported date does not automatically establish the deduction amount. The business may still need to determine:
- whether the cost must be capitalized;
- the correct depreciable basis;
- business-use percentage;
- asset class and recovery period;
- applicable convention;
- Section 179 eligibility and limits;
- bonus-depreciation eligibility and elections;
- vehicle or listed-property restrictions; and
- whether related-party, used-property or other exclusions apply.
Current IRS guidance provides a permanent 100% additional first-year depreciation rule for certain eligible property acquired after January 19, 2025. Eligibility still depends on the property and transaction facts. Our 2026 bonus depreciation guide covers that separate analysis, and the 2026 Section 179 guide explains additional limits.
Do not promise a full write-off based only on a purchase date or vendor advertisement.
Coordinate purchasing with bookkeeping
Create a capital-purchase checklist before the fourth quarter closes. For each item, record:
- vendor and asset description;
- serial or identifying number;
- total cost and financing details;
- expected delivery and installation dates;
- responsible employee or contractor;
- actual ready-and-available date;
- supporting file location;
- business-use percentage; and
- unresolved tax classification questions.
Reconcile the fixed-asset register to accounts payable, loan records and cash payments. Separate deposits on future equipment from assets already received and ready. A deposit may be a balance-sheet item rather than a depreciable asset placed in service.
Tax N Tips can help Houston businesses organize monthly bookkeeping, review equipment purchase records and prepare business tax filings. Book a consultation before year-end when a major purchase still needs installation, testing or documentation.
Sources checked September 16, 2026: IRS Publication 946 (2025), How To Depreciate Property, IRS Topic No. 704, Depreciation, and IRS Notice 2026-11 announcement on additional first-year depreciation. Publication 946 is the current posted publication for the general placed-in-service rule; current 2026 law and asset-specific guidance control the final treatment.
More tax tips

Marketplace sales reconciliation for 2026: gross sales to bank deposits
A practical 2026 reconciliation for marketplace sellers to connect gross sales, refunds, fees, shipping, sales tax and net bank deposits.
Read the guide
2026 Form 1099-K threshold: what changed and what did not
The 2026 Form 1099-K threshold returned to $20,000 and more than 200 transactions for payment apps and marketplaces, but business income rules did not change.
Read the guide
Fix contractor payment records before filing 2026 Forms 1099-NEC
A Houston small-business checklist for correcting contractor names, taxpayer IDs, payment totals and duplicates before 2026 Forms 1099-NEC are filed.
Read the guide